When a company starts missing payments, directors often focus on survival and overlook their own legal exposure. Under India’s insolvency framework, the decisions a board makes in the months before a filing can follow a director personally for years. At Escalade Legal Services, an ip law firm in Bangalore with a strong corporate practice, we regularly advise boards on how to act when finances weaken. A trusted corporate law firm in Bangalore can help you understand your duties, limit personal risk and choose the right path before creditors choose it for you.
What Is Corporate Insolvency in India?
Corporate insolvency means a company cannot pay its debts as they fall due. In India, the process is governed mainly by the Insolvency and Bankruptcy Code, 2016 (IBC), which replaced a slow and fragmented system with a time-bound framework run before the National Company Law Tribunal (NCLT).
The IBC has two main outcomes:
- Corporate Insolvency Resolution Process (CIRP): an attempt to revive the company by finding a buyer or an investor with a resolution plan.
- Liquidation: if no plan succeeds, the company’s assets are sold and the proceeds are distributed to creditors under a fixed order of priority.
The Code aims to maximise the value of the business, balance the interests of all stakeholders and keep credit flowing in the economy. For directors, it also changes the rules of the game in a significant way.
How Does the Insolvency Process Begin?
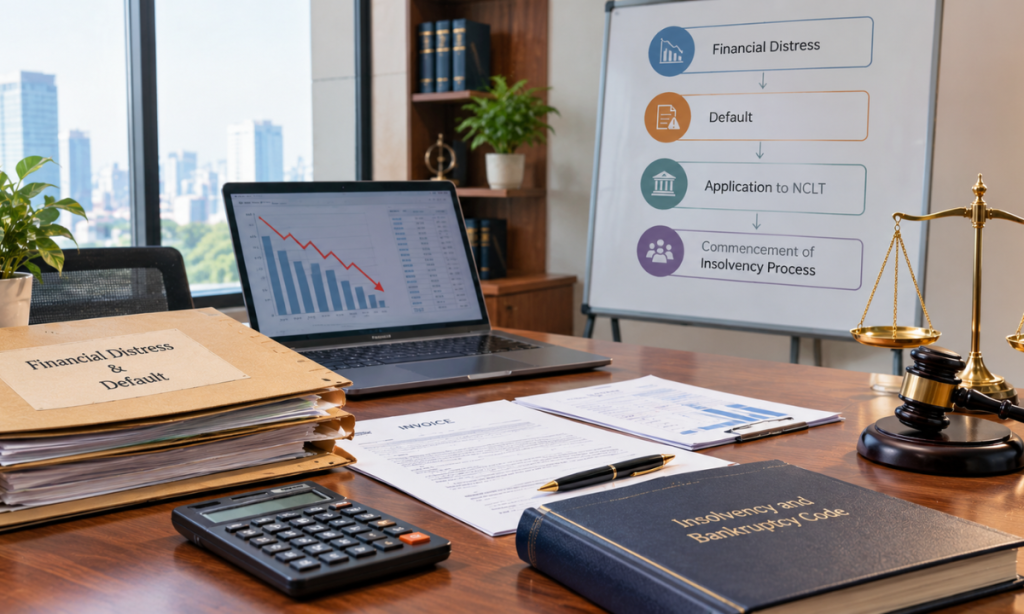
A CIRP can be started by:
- A financial creditor such as a bank or lender, under Section 7
- An operational creditor such as a supplier or service provider, under Section 9
- The company itself (a corporate applicant), under Section 10
The minimum default amount needed to initiate CIRP is Rs 1 crore. Once the NCLT admits the application, a moratorium begins, which stops suits, recoveries and enforcement actions against the company. The CIRP is meant to conclude within 180 days, extendable by up to 90 days, with an overall outer limit of 330 days including litigation time.
What Happens to the Board When CIRP Begins?
This is the point directors need to understand most clearly. On admission of the application:
- The powers of the board are suspended. They pass to an Interim Resolution Professional (IRP), who later may be confirmed as the Resolution Professional (RP).
- Management is displaced. The directors no longer run the company, sign cheques or make strategic decisions.
- Directors must cooperate. Under Section 19, directors and officers must give the IRP full assistance, including records, accounts and access to premises. Failure to cooperate can lead to penalties.
- Promoters face restrictions. Under Section 29A, certain persons, including defaulting promoters and those linked to non-performing accounts, are barred from submitting a resolution plan for the company.
Directors remain responsible for the period before admission, and the RP is required to examine what happened during that time.
The Twilight Period and Wrongful Trading
The most important concept for directors is the “twilight period”, the stretch before insolvency when failure becomes likely. During this time, the duty of directors is understood to shift towards protecting creditors.
Wrongful trading under Section 66(2)
A director can be asked by the NCLT to contribute personally to the company’s assets if:
- Before the insolvency commencement date, the director knew or ought to have known that there was no reasonable prospect of avoiding insolvency, and
- The director did not exercise due diligence to minimise the potential loss to creditors.
The test looks at what a reasonably diligent person with the same knowledge and skill would have done. Directors who keep trading, take on fresh credit or pay favoured parties while ignoring obvious distress are at real risk.
Fraudulent trading under Section 66(1)
If the business was carried on with intent to defraud creditors or for any fraudulent purpose, the persons knowingly involved can be made liable to contribute to the company’s assets. This applies to directors and any other person who knowingly took part.
Transactions an RP Can Challenge
The RP is obliged to review specific transactions and, where appropriate, ask the NCLT to reverse them. These include:
- Preferential transactions (Section 43): payments or transfers that put certain creditors or related parties in a better position during the look-back period.
- Undervalued transactions (Section 45): assets sold or transferred for far less than fair value.
- Extortionate credit transactions (Section 50): credit on unconscionable terms.
- Transactions defrauding creditors (Section 49): deals made to keep assets away from creditors.
Transactions with related parties, which include directors and group companies, face particular scrutiny. Clean records, board approvals and fair valuations are a director’s best protection. Careful contract drafting review services before major agreements are signed help ensure that deals can survive a later challenge.
Personal Liability: Where Directors Are Exposed
Directors are not ordinarily liable for company debts, because a company is a separate legal person. However, the IBC and related laws create several routes to personal exposure.
| Source of risk | What it means for a director |
| Wrongful trading (Section 66(2)) | Court-ordered personal contribution to the company’s assets |
| Fraudulent trading (Section 66(1)) | Personal liability and possible criminal consequences |
| Personal guarantees | Creditors can pursue the guarantor directly, and personal guarantors to corporate debtors can face proceedings under the Code |
| Non-cooperation with the IRP | Penalties under the Code |
| Companies Act breaches | Fines, disqualification under Section 164 and, in cases of fraud, more serious action under Section 447 |
| Tax and statutory dues | Other laws can impose liability on directors independently of the IBC |
Courts have also indicated that approval of a resolution plan does not automatically wipe out a director’s personal penal liability under other statutes. A director should therefore never assume that insolvency itself closes every risk.
Practical Steps Directors Should Take When Distress Appears
Early, documented action is the strongest defence. Boards should:
- Get an honest financial picture. Review cash flow, receivables, debt maturities and contingent liabilities every month.
- Hold regular, minuted board meetings. Record the information considered and the reasons for each decision.
- Stop incurring credit with no realistic prospect of repayment. Taking fresh supplies or loans while insolvent is a major red flag.
- Treat creditors fairly. Avoid paying related parties or favoured lenders ahead of others without a sound commercial reason.
- Seek independent advice early. Engage legal and financial advisers before a creditor files, not after.
- Explore negotiated solutions. Debt restructuring, one-time settlements and out-of-court arrangements can preserve value. Strong corporate governance compliance practices make it easier to show that the board acted responsibly throughout.
- Keep statutory filings current. Missed annual returns can lead to disqualification, which compounds an insolvency problem.
- Preserve records. Accounts, minutes, correspondence and approvals will be examined by the RP.
Alternatives Before Full Insolvency
Directors often have more choices than they realise:
- Negotiated restructuring or settlement with lenders and key suppliers
- Settlement after filing: an admitted application can be withdrawn under Section 12A if the Committee of Creditors approves with the required majority
- Pre-packaged insolvency (PPIRP) for eligible micro, small and medium enterprises, which offers a faster and less disruptive process
- Fast-track CIRP for eligible smaller companies
- Voluntary liquidation for solvent companies that wish to close in an orderly way
Choosing the right route depends on the size of the debt, the quality of the business and the position of key creditors. Where creditors are already pressing claims, experienced counsel for corporate dispute resolution can negotiate, defend claims before the NCLT and protect the board’s position.
Insolvency and the Workforce
Insolvency affects employees as much as lenders. Salary arrears, provident fund dues and gratuity claims all rank in the distribution of assets, and directors need to understand which dues receive priority. Questions about notice periods, retrenchment and continued employment during CIRP require careful handling, and specialist employment labour law advice helps the company stay compliant while the process runs.
Intellectual Property in Insolvency
For many Bangalore businesses, particularly technology and consumer brands, the most valuable assets are not machinery or property but intellectual property. Trademarks, patents, software code, copyrights and licences are all assets of the corporate debtor. The RP must identify, protect and value them, and bidders for the business often care more about the IP than anything else.
This is where specialised support matters. An experienced ip law firm in Bangalore can confirm that registrations are valid, that renewals are paid and that ownership is properly documented, because gaps in title can reduce the value of the business in a resolution process. Qualified ip lawyers in Bangalore can also review licences, assignments and security interests so that critical rights are not lost during a moratorium. Directors who have already filed their marks and inventions through trademark registration in Bangalore and patent registration in Bangalore will be in a far stronger position.
Preventing Insolvency Problems from the Start
Many insolvency disputes trace back to weak foundations. Businesses that begin with proper company formation compliance services, clear shareholder arrangements and disciplined record keeping are better prepared when conditions turn. Early-stage companies should also consider advice from startup lawyers in Bangalore on founder liability, personal guarantees and borrowing limits before taking on debt.
How Escalade Legal Services Supports Directors in Financial Distress
Escalade Legal Services is led by Venkata Raghavan, an IP lawyer with more than 18 years of experience and an LLM from the University of California. He is enrolled with the Karnataka State Bar Council, is a member of the International Trademark Association and the Asian Patent Attorneys Association, and is registered as a foreign lawyer before the Singapore International Commercial Court. That cross-border exposure is useful when creditors, assets or counterparties sit outside India.
For directors facing insolvency pressure, the firm’s support typically includes:
- Personal exposure review: checking guarantees, related party dealings and recent transactions that an RP may question
- Creditor negotiation and settlement strategy: structuring talks before a petition is filed, or after one is admitted
- Representation in disputes: handling notices, claims and proceedings before the tribunal and courts
- Board documentation: minutes, approvals and compliance records that show diligent decision making
- IP protection and valuation support: securing trademarks, patents and licences so that the value of the business is preserved
- Practical, cost-conscious advice for startups and established companies, as a registered start-up facilitator under the Digital India Programme
When insolvency pressure threatens both your board and your brand, a dependable corporate law firm in Bangalore that also understands IP can address both together.
Frequently Asked Questions
Are directors personally liable for a company’s debts in insolvency?
Not automatically. A company is a separate legal entity. However, directors can be personally liable for wrongful or fraudulent trading, for personal guarantees they have given, and for breaches of other laws.
What happens to directors once CIRP starts?
The board’s powers are suspended and an insolvency professional takes control. Directors must still cooperate fully and provide information and records.
What is the twilight period?
It is the period before insolvency when a director knew or should have known that insolvency was unavoidable. Directors are expected to act to minimise losses to creditors during this time.
Can directors stop an insolvency case after it is filed?
Sometimes. A settlement with the creditor and approval by the required majority of the Committee of Creditors can allow withdrawal under Section 12A. Early negotiation improves the chances.
Can promoters bid for their own company?
Section 29A bars certain persons from submitting a resolution plan, including those who are wilful defaulters or are connected with non-performing accounts. Eligibility must be reviewed carefully.
Does insolvency affect the company’s intellectual property?
Yes. IP is an asset of the corporate debtor and is valued and dealt with in the process. Valid registrations and clean ownership records protect its value.
Final Thoughts
Corporate insolvency tests directors more than it tests balance sheets. The IBC does not punish a company for failing, but it does look hard at how the board behaved while failure approached. Directors who watched cash flow closely, recorded their decisions, treated creditors evenly and sought advice early generally have far more room to protect themselves. Those who kept trading blindly, favoured insiders or ignored warning signs often find the tribunal asking them for answers, and sometimes for money.
Three points are worth carrying forward. First, your exposure is shaped by what you did in the twilight period, not only after a petition is filed. Second, suspension of the board does not end your duty to cooperate, and it does not end every liability. Third, options such as settlement, pre-packaged insolvency or orderly restructuring are most useful when they are explored early.
If your company is dealing with delayed payments, lender notices or a creditor demand, do not wait for a petition to arrive. A focused review by a corporate law firm in Bangalore can map your personal risk, set out your options and put a clear decision trail in place from today.
Facing Creditor Pressure? Speak to a Director Risk Counsel Before Your Next Board Meeting
Financial distress calls for fast, informed decisions, and every decision made now will be examined later. Escalade Legal Services brings corporate, dispute and IP advice together, so you can assess your liability as a director, negotiate with lenders, respond to a tribunal notice and safeguard your company’s brands and technology, all through one team.
Schedule a Legal Consultation on Corporate Insolvency and Director Liability
If you need to review your personal exposure, plan a restructuring or settlement with creditors, or protect your company’s intellectual property while a resolution is underway, connect with the corporate and IP attorneys at Escalade Legal Services:
- Headquarters: Escalade Legal Services, Chambers 401, DBS House Business Centre, No. 26, Cunningham Road, Bengaluru, Karnataka 560052
- New Delhi Office: World Trade Towers, Barakhamba Lane, Connaught Place, New Delhi 110001
- Official Website: escaladelegal.com
- Direct Contact: +91 96110 57021 / escalade@escaladelegal.com
Acting early, documenting every decision and getting the right advice today can mean the difference between a managed restructuring and a personal liability claim tomorrow.