Corporate restructuring in India involves changing a company’s ownership, business structure, assets or liabilities to meet strategic and financial goals. It may include mergers, demergers, amalgamations, acquisitions or capital restructuring. The process requires careful planning, legal approvals, regulatory compliance and protection of shareholder and creditor interests.
Introduction
Businesses may need to restructure to expand operations, separate business divisions, reduce financial pressure, attract investors or improve operational efficiency. Corporate restructuring provides a legal framework for making these changes while managing the interests of shareholders, employees, creditors and other stakeholders. Companies planning such transactions may consult a corporate law firm in Bangalore to understand the applicable laws, approvals and documentation.
The right restructuring method depends on the company’s objectives, financial position, ownership structure and regulatory obligations. A well-planned process can help businesses improve efficiency, manage risk and prepare for future growth.
What Is Corporate Restructuring?
Corporate restructuring is the process of changing a company’s legal, financial, operational or ownership structure. It may involve combining companies, transferring business undertakings, separating divisions, changing share capital or reorganising debt.
Restructuring can be undertaken by financially stable businesses pursuing growth as well as companies addressing financial or operational difficulties. The method selected should support the business objective while complying with applicable corporate and regulatory laws.
Types of Corporate Restructuring in India
1. Mergers and Amalgamations
A merger combines two or more businesses into one corporate structure. Depending on the arrangement, one company may absorb another, or the businesses may combine through a new entity.
Amalgamation generally involves combining companies, with the assets and liabilities of the transferor company or companies passing to the resulting company under the approved scheme.
Businesses may consider mergers and amalgamations to expand their market presence, combine resources, reduce duplication or improve operational efficiency. These transactions commonly require due diligence, a valuation exercise, shareholder and creditor considerations, and statutory approvals.
2. Demergers
A demerger separates a business division or undertaking from an existing company and transfers it to another company, often a newly incorporated entity. The purpose may be to separate unrelated operations, improve management focus or allow each business to pursue a distinct growth strategy.
For example, a company operating manufacturing and technology divisions may separate these businesses into independent entities. The restructuring scheme must address the transfer of assets, liabilities, employees, contracts and other relevant rights.
The legal, accounting and tax treatment depends on the transaction structure and the conditions prescribed under applicable law.
3. Acquisitions and Takeovers
An acquisition occurs when one company or investor obtains control over another company or acquires its shares or business assets. A takeover may involve acquiring a controlling stake or gaining control through other permitted arrangements.
These transactions require careful review of ownership rights, existing contracts, liabilities, regulatory restrictions and competition concerns. Listed-company acquisitions may also trigger disclosure and open-offer requirements under applicable Securities and Exchange Board of India (SEBI) regulations.
4. Capital Restructuring
Capital restructuring changes a company’s share capital or financing arrangements. It may involve a share capital reduction, consolidation or subdivision of shares, fresh equity issuance, buybacks or changes to debt and equity proportions.
Companies may use these measures to reorganise ownership, address accumulated losses, improve their capital structure or raise funds. Each method has its own statutory conditions and approval requirements.
5. Financial and Debt Restructuring
Financial restructuring changes how a company manages its borrowings and financial obligations. It may involve revising repayment schedules, renegotiating loan terms, refinancing debt or converting eligible debt into equity.
Companies must consider lender agreements, security interests, creditor rights and applicable insolvency laws. Where a company is unable to pay its debts, the Insolvency and Bankruptcy Code, 2016 may become relevant. A negotiated restructuring should not be treated as a substitute for insolvency proceedings where statutory conditions require a different approach.
Legal Framework Governing Corporate Restructuring
The Companies Act, 2013 is a key law governing corporate restructuring in India. Chapter XV, particularly Sections 230 to 234, addresses compromises, arrangements, mergers and amalgamations.
The principal provisions include:
- Section 230: Provides for compromises and arrangements between a company and its creditors or members, subject to statutory requirements.
- Section 231: Gives the National Company Law Tribunal (NCLT) powers to supervise and enforce approved arrangements in accordance with the law.
- Section 232: Covers schemes involving mergers, amalgamations and certain transfers or divisions of undertakings.
- Section 233: Provides a simplified merger route for eligible companies, subject to prescribed conditions and approvals.
- Section 234: Addresses mergers and amalgamations involving foreign companies, subject to applicable law and regulatory requirements.
Depending on the transaction, other laws may also apply. These include the Competition Act, 2002, the Income-tax Act, 1961, the Foreign Exchange Management Act, 1999, SEBI regulations and sector-specific legislation.
The applicable requirements depend on the companies involved, the transaction structure and the nature of the business. Not every restructuring requires the same approvals or follows the same procedure.
Corporate Restructuring Process in India
Step 1: Define the Business Objective
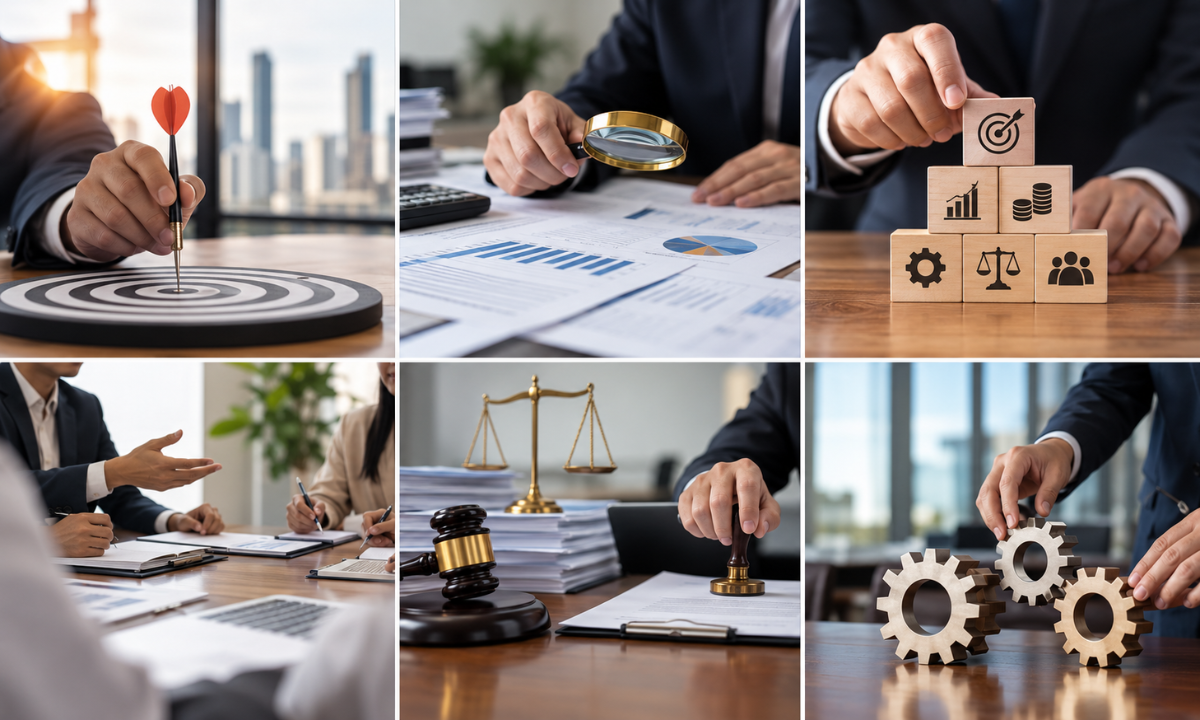
The company should identify why restructuring is necessary. Objectives may include business expansion, separation of divisions, debt reduction, ownership changes or operational consolidation.
The proposed structure should be assessed against the company’s commercial goals, financial position and long-term plans.
Step 2: Conduct Legal and Financial Due Diligence
Due diligence helps identify liabilities, pending litigation, contractual restrictions, tax exposure, regulatory issues and ownership concerns.
The review should cover financial statements, borrowing arrangements, material contracts, intellectual property, employee obligations, licences and statutory filings. Where necessary, the company should also review whether existing agreements require consent before assets, shares or business operations can be transferred.
Step 3: Determine the Restructuring Structure and Valuation
The company must select an appropriate legal route and assess the value of the businesses, assets or shares involved. Independent valuation may be required under applicable law or transaction-specific rules.
The restructuring scheme should clearly explain the proposed transfers, consideration, share exchange ratio where relevant, treatment of liabilities and the expected effect on shareholders and creditors.
Step 4: Obtain Board, Shareholder and Creditor Approvals
The company’s board must consider and approve the proposed transaction in accordance with the applicable requirements. Shareholder and creditor approvals may also be required.
For schemes under Sections 230 and 232, the NCLT may direct meetings of relevant classes of members or creditors, subject to the statutory framework. The required voting thresholds and procedures depend on the applicable provisions and the Tribunal’s directions.
Step 5: Secure Regulatory Approvals
Depending on the transaction, approvals or representations may involve the NCLT, Registrar of Companies, Regional Director, tax authorities, the Competition Commission of India, SEBI, stock exchanges, the Reserve Bank of India or other regulators.
A merger involving eligible companies may qualify for the fast-track procedure under Section 233. Cross-border transactions require additional consideration of foreign exchange rules and other applicable restrictions.
Step 6: Complete Filings and Implement the Scheme
Once the necessary approvals are obtained, the companies must complete the required filings and implement the approved scheme. This may involve transferring assets and liabilities, issuing shares, updating statutory registers, amending corporate records and notifying relevant stakeholders.
The companies should also review tax filings, accounting treatment, employee arrangements, contracts and licences to ensure that the approved restructuring is implemented correctly.
Key Legal and Regulatory Considerations
Corporate restructuring requires more than an agreement between the companies involved. Businesses should pay particular attention to the following areas:
- Shareholder and creditor rights: Ensure that affected parties receive the notices, information and protections required by law.
- Tax implications: Assess capital gains, tax neutrality conditions, carry-forward of losses and other consequences under the Income-tax Act.
- Competition law: Determine whether the transaction requires approval or notification under the Competition Act and applicable merger-control rules.
- Foreign investment and exchange control: Review FEMA requirements, foreign investment conditions and Reserve Bank of India rules where cross-border elements are involved.
- Contracts and liabilities: Identify change-of-control clauses, lender consents, guarantees, pending disputes and obligations that may transfer under the scheme.
- Corporate governance: Maintain proper board records, disclosures, valuation documents and statutory filings throughout the process.
Companies should also consider employee communication, business continuity, data access and the integration of systems after the restructuring takes effect.
Common Challenges in Corporate Restructuring
Restructuring can be delayed by valuation disagreements, incomplete due diligence, creditor objections, regulatory queries or unclear transaction terms. Tax uncertainty and contractual restrictions can also affect the proposed structure.
Businesses can reduce these risks by identifying legal issues early, preparing accurate financial information, documenting the commercial rationale and creating a clear implementation plan. Coordination among legal, finance, tax and business teams is important throughout the transaction.
Corporate Restructuring Checklist for Indian Businesses
Before starting a corporate restructuring, companies should review the following checklist to identify legal, financial and operational requirements.
1. Business Planning
- Define the purpose of restructuring and the expected business benefits.
- Identify the appropriate structure, such as a merger, demerger, acquisition or capital restructuring.
- Assess the financial position, ownership structure and long-term business objectives.
2. Legal and Financial Due Diligence
- Review financial statements, existing loans and outstanding liabilities.
- Identify pending litigation, regulatory issues and contractual restrictions.
- Verify ownership of assets, intellectual property, licences and other business rights.
- Assess employee obligations and existing creditor arrangements.
3. Valuation and Documentation
- Obtain a valuation and determine the share exchange ratio or transaction consideration, where applicable.
- Prepare the restructuring scheme, agreements and supporting documents.
- Assess tax implications and eligibility for any applicable tax benefits.
- Document the commercial rationale and proposed treatment of assets and liabilities.
4. Approvals and Regulatory Compliance
- Obtain board approval and identify the required shareholder and creditor approvals.
- Determine whether NCLT approval or a fast-track merger procedure is applicable.
- Check competition law, SEBI, FEMA, RBI and sector-specific requirements, where relevant.
- Prepare and submit the necessary notices, applications and statutory filings.
5. Implementation and Post-Restructuring Compliance
- Complete the required filings with the Registrar of Companies and other authorities.
- Transfer assets, liabilities, contracts and employees according to the approved arrangement.
- Update shareholding records, statutory registers, accounting records and tax registrations, as applicable.
- Communicate relevant changes to employees, lenders, customers and business partners.
- Monitor post-restructuring obligations, reporting deadlines and continuing regulatory compliance.
Practical Tip: The checklist should be tailored to the proposed transaction. Not every restructuring requires all the approvals listed above. The applicable requirements depend on the transaction structure, the companies involved and the relevant laws.
Conclusion
Corporate restructuring can help Indian businesses reorganise operations, improve financial stability, separate business divisions or pursue strategic growth. However, the appropriate method depends on the company’s objectives, ownership, liabilities and regulatory position.
Understanding the available restructuring options and the requirements under the Companies Act, 2013 and other applicable laws helps businesses plan transactions with greater clarity. Proper due diligence, suitable valuation, timely approvals and careful implementation are essential to completing a restructuring in a legally compliant manner.
This article is for general informational purposes only and does not constitute legal or tax advice. Requirements vary according to the facts and structure of each transaction.